BEGIN:VCALENDAR
PRODID:-//TERMINALFOUR//SITEMANAGER V7.3//EN
VERSION:2.0
BEGIN:VEVENT
DTSTART:20241127T110000
LOCATION:Braamfontein Campus West New Commerce Building (NCB), Room 221
DESCRIPTION:SEF invites you to a presentation by Prof. Darko B. Vukovic on Advanced Modeling of Volatility Spillovers: Dynamic Bayesian GVAR and Fourier-Augmented MethodsJoin the meeting now
Speaker Profile:
Prof. Darko B. Vukovic Chief Expert (Scientific director) in the Centre for Market efficiency and applied finance, GSOM, SPB, Russia
Dr. Darko B. Vukovic has over 15 years of experience teaching finance courses at the postgraduate, graduate (master in corporate finance, CFA, ACCA, AMBA, AACSB accreditations), and undergraduate levels at different global universities. He also serves as the Head of the International Laboratory for Finance and Financial Markets at the Faculty of Economics, People’s Friendship University of Russia. His research interests include digital finance, financial markets, financial forecasting, machine learning in finance, financial risk management, and investment finance.
His research has been awarded multiple times, like the Emerald Literati Award 2021 for “Outstanding Paper” (UK) and from Wiley, Top Cited Article in 2020-2021 (the journal Internet technology letters). He has published more than 70 papers indexed in leading index databases: Web of Science, Scopus, and ABS (CABS). During his career, he has reviewed numerous journals of leading publishing houses (Tayler & Francis, Elsevier, Springer, Chapman & Hall/CRC Press, Emerald, Sage, etc.) and has been several times a guest editor in international journals. Currently he is a member of The American Southern Finance Association (Jacksonville, US) and Southwestern Finance Association (Huston, US). He serves as a visiting professor at La Salle University, Bogota, Columbia and Fudan School of Economics, Fudan University, Shanghai, China.
X-ALT-DESC;FMTTYPE=text/html:SEF invites you to a presentation by Prof. Darko B. Vukovic on Advanced Modeling of Volatility Spillovers: Dynamic Bayesian GVAR and Fourier-Augmented Methods
Speaker Profile:
Prof. Darko B. Vukovic
Chief Expert (Scientific director) in the Centre for Market efficiency and applied finance, GSOM, SPB, Russia
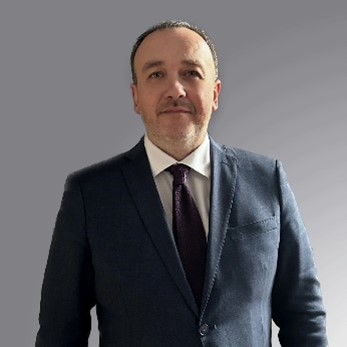
Dr. Darko B. Vukovic has over 15 years of experience teaching finance courses at the postgraduate, graduate (master in corporate finance, CFA, ACCA, AMBA, AACSB accreditations), and undergraduate levels at different global universities. He also serves as the Head of the International Laboratory for Finance and Financial Markets at the Faculty of Economics, People’s Friendship University of Russia. His research interests include digital finance, financial markets, financial forecasting, machine learning in finance, financial risk management, and investment finance.
His research has been awarded multiple times, like the Emerald Literati Award 2021 for “Outstanding Paper” (UK) and from Wiley, Top Cited Article in 2020-2021 (the journal Internet technology letters). He has published more than 70 papers indexed in leading index databases: Web of Science, Scopus, and ABS (CABS). During his career, he has reviewed numerous journals of leading publishing houses (Tayler & Francis, Elsevier, Springer, Chapman & Hall/CRC Press, Emerald, Sage, etc.) and has been several times a guest editor in international journals. Currently he is a member of The American Southern Finance Association (Jacksonville, US) and Southwestern Finance Association (Huston, US). He serves as a visiting professor at La Salle University, Bogota, Columbia and Fudan School of Economics, Fudan University, Shanghai, China.
SUMMARY:Advanced Modeling of Volatility Spillovers
END:VEVENT
END:VCALENDAR